Trump Education Department Student Loan Caps Reshape Graduate Borrowing Rules
“I think right now, though, it’s really kind of the wild west. Everybody’s just trying to figure it out.”
Jack Wang, Wealth Advisor at Innovative Advisory Group
Beginning July 1, 2026, new federal borrowing limits changed how graduate and professional students can finance their degrees. Most new graduate borrowers can receive no more than $20,500 in federal loans each year, with a $100,000 aggregate limit. Students enrolled in programs classified by the Education Department as professional degrees can borrow up to $50,000 annually and $200,000 in total.
The policy also ends Grad PLUS for new borrowers. The program previously allowed graduate students to cover their school’s full cost of attendance after other federal aid, including tuition and living expenses that exceeded the standard annual loan limit. Students already enrolled and borrowing for the same program generally retain the previous terms for the remaining expected length of their degree, leaving incoming students to navigate the new system first.
For programs costing more than the federal ceiling, the difference must now come from scholarships, institutional aid, savings, employment, or private loans. That gap can open before rent, transportation, and other living expenses are added. A student may have the academic credentials to enter a program and a clear path into a needed profession, but still be unable to enroll without a co-signer or additional family support.
The Trump administration argues that access to open-ended federal borrowing allowed universities to raise tuition while students accumulated debts their earnings could not support. Officials expect the caps to pressure institutions to reduce prices and encourage borrowers to examine the financial return of a degree more closely. Whether schools lower their costs remains uncertain. If they do not, more of the burden shifts to students, their families, and private lenders.
The amount available also depends on how the Education Department defines the degree itself. A student in a designated professional program can borrow $29,500 more each year than someone classified as a graduate student, giving what once seemed a technical distinction a direct role in determining who can afford advanced training.
To better understand how the new limits may reshape graduate enrollment, family finances, and access to advanced degrees, we spoke with college financial aid expert Jack Wang about what happens when federal loans no longer cover the full cost of a program.
Meet the Expert: Jack Wang, Wealth Advisor at Innovative Advisory Group
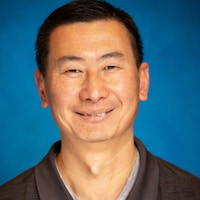
Jack Wang is a college financial aid expert, wealth advisor, and host of the Smart College Buyer podcast. He helps families evaluate college costs, maximize financial aid, and build strategies for paying tuition without undermining their broader financial goals. His work focuses on college affordability, student debt, financial aid planning and the tradeoffs families face when education costs compete with retirement and everyday expenses.
Wang is a wealth advisor at Innovative Advisory Group and holds a bachelor’s degree in finance from the University of Texas at Austin. Through his advisory work and podcast, he provides guidance on scholarships, grants, federal and private student loans, college-list building, and the financial implications of higher education policy changes.
Who Counts as a Professional Student?
The federal government is no longer simply deciding how much graduate students may borrow. It is also deciding which forms of advanced training merit greater support.
The Education Department initially places medicine, dentistry, law, pharmacy, veterinary medicine and certain theological degrees in the higher borrowing tier. Graduate programs in nursing, physician associate studies, speech-language pathology, occupational therapy and physical therapy do not receive the same designation, despite requiring clinical training, professional licensing and, in many cases, several years of education beyond a bachelor’s degree.
That line is now under legal challenge.
On June 24, a federal judge temporarily stayed the department’s narrower definition and extended professional-degree status to several nursing, therapy, psychology and allied-health programs. The ruling does not eliminate the new caps or restore Grad PLUS. Instead, it changes which students can reach the higher limit while the case proceeds.
Even that relief is uncertain. The Education Department warns that future court action may alter the list again and allows universities to keep newly eligible students under the lower cap. A nursing or physical therapy student may therefore qualify for additional federal financing in principle but receive less if the institution decides not to revise its lending policy during the dispute.
The professions at the center of the case are not demographically neutral. Women comprise most registered nurses, occupational therapists, speech-language pathologists, physician associates and physical therapists. The rule does not mention gender, but its original boundaries place several female-dominated health and care fields below professions such as medicine, dentistry and law.
For students, the legal distinction quickly becomes a question of what they can afford to enroll in. “One is to either go to a less expensive program,” Wang explains. When savings and borrowing are insufficient, he adds, “the parents are gonna have to be involved.”
That involvement changes the basis of graduate-school access. Once federal aid stops covering the cost, the next decision belongs less to the university than to the student’s household and, increasingly, to the private lender evaluating it.
When Graduate Debt Burden Shifts to the Family
For students whose programs cost more than the federal limit, the next step is not simply borrowing elsewhere. It is entering a private lending system that evaluates whether the student, or someone in the family, is financially strong enough to take on the debt.
Federal graduate loans have generally been available without the income and credit requirements banks use. Private lenders examine credit scores, existing obligations, and debt-to-income ratios. Because many graduate students have limited earnings and little borrowing history, approval may depend on a parent or relative co-signing.
“It’s going to involve the whole family, and it’s gonna involve everyone’s finances in a more holistic sense, much more than it has been,” Wang says.
That shift creates an immediate barrier for students from lower-income and first-generation households. A parent may support the degree but lack the financial profile a lender requires. “Low-income families are less likely to credit qualify,” Wang explains, particularly when housing and other essential expenses already consume much of the household’s earnings.
In those cases, the student may not receive a more expensive loan at a higher rate. The loan may not be available at all. The remaining choices are a lower-cost program, part-time enrollment, delaying the degree, or abandoning it.
Families with higher incomes face a different calculation. Some may qualify on paper while already living with little room in their monthly budgets. Taking on another obligation can reduce retirement contributions, delay retirement, or crowd out other spending long after the student finishes school.
Wang recently worked with parents approaching repayment on nearly $400,000 in Parent PLUS loans for an undergraduate education. Their expected bill is about $3,500 a month. The case is not a result of the new graduate limits, but it shows why qualifying to borrow and being able to repay are not the same.
“They’re like, ‘If we have to pay this, we’re not gonna be able to retire because we can’t afford $3,500 a month,’” Wang says.
The financing gap therefore separates families in two ways. Some cannot obtain the credit needed to enroll. Others can borrow enough to proceed but absorb the consequences later. As those decisions accumulate, the effects move beyond household budgets and begin reshaping which programs universities can sustain and which borrowers private lenders are willing to serve.
Universities and Lenders Enter an Unsettled Market
As more families turn to private credit, the uncertainty spreads through the rest of the graduate education market. Lenders must decide which borrowers to approve without a clear record of how former Grad PLUS users perform under conventional underwriting. Universities, meanwhile, must determine how many students can still finance enrollment once federal loans stop at a fixed ceiling.
“Nobody really knows how many students who borrowed using Grad PLUS for grad school would credit qualify for a private loan, or their families,” Wang shares.
Grad PLUS did not require the same review of income, credit history, and debt obligations used by private lenders, leaving banks with limited information about the population now moving into their market.
The first few enrollment cycles may therefore produce wide differences in what students are offered. Some lenders may loosen terms to build market share, while others price loans more cautiously until repayment data shows which borrowers present the greatest risk. Wang expects students who compare offers to encounter meaningful variation in rates and conditions.
“I think right now, though, it’s really kind of the wild west, like, everybody’s just trying to figure it out,” he states.
Universities face a different version of the same uncertainty. Expensive programs in fields with modest starting salaries become harder to justify when students must cover a larger share of the cost privately. Wang expects degrees such as teaching and social work to remain available, but says higher-priced versions may struggle as students move toward regional public universities and other lower-cost options.
Enrollment pressure will not fall evenly. Wealthy institutions can increase grants, draw on endowments or explore agreements that reduce a lender’s risk. Wang says some schools have discussed loss-sharing arrangements in which the university absorbs part of a lender’s losses if students default. Borrowers may never see those contracts, but the arrangements could help institutions preserve access to credit and protect enrollment.
Schools without large reserves have fewer options. They can reduce tuition, shrink programs, accept lower enrollment or hope students find another source of financing. The policy may therefore widen the divide not only between families, but between universities able to support private borrowing and those forced to absorb the full effect of the federal limits.
What emerges is a graduate market shaped as much by price and institutional resources as by academic demand. Students will still choose professions, but universities and lenders will increasingly determine which versions of those degrees remain financially reachable.
Could Cost Become Part of the Admissions Decision?
The new borrowing limits change when students must confront the cost of graduate school. Financing can no longer remain a question to resolve after admission. For many applicants, it now determines which programs belong on the list at all.
Wang says families rarely approach education the way they approach other major purchases. Someone looking for a car or a home usually establishes a price range before deciding what to see. College applicants often begin with reputation, location, or curriculum and calculate the cost only after narrowing their choices.
“If you’re in the market for like a $30,000 car, you’re probably not going to the Ferrari dealership,” Wang says. Yet with colleges, he adds, “people don’t really do that when it comes to colleges and building college lists, whether it’s graduate school or undergraduate.”
The difference matters because a financing plan must cover the entire degree. A scholarship may apply for only one year. Savings can run out. Private lenders can change their terms, and a parent willing to co-sign one loan may be unable or unwilling to assume another.
One family Wang advises confronts that problem as a daughter chooses between a local graduate program and a private alternative costing roughly twice as much. Federal borrowing and the student’s savings can cover the nearby option. The more expensive program leaves a recurring gap, and the parent has already ruled out co-signing additional debt.
“Unless you have a plan for coming up with the rest of the money each year, right, not just one year, but each year, then, like, why are you looking?” Wang says. “I’m not trying to crush your dreams, but if you don’t have the ability to pay for it, then why are you, like, torturing yourself by even thinking about it?”
Universities may also begin treating affordability as part of enrollment strategy. A school that admits a student but leaves a large unfunded balance risks losing that student before classes begin. Institutions trying to protect enrollment could increase grants, offer tuition discounts, restructure programs around part-time study, or direct more aid toward degrees that become difficult to finance under the lower cap. How much support they can provide will depend heavily on their own financial resources.
That calculation does not necessarily push students away from teaching, social work, healthcare, or other professions requiring graduate study. It may instead redirect them toward regional public universities, nearby campuses, part-time study or programs able to provide more institutional aid. Demand for the degree remains, but the institutions capturing that demand may change.
The administration expects this pressure to force universities to lower prices. That outcome depends on whether schools can reduce costs or increase aid before students withdraw or choose competitors. Otherwise, the caps produce a different form of discipline: expensive programs remain available, but increasingly to applicants whose families can supply cash, qualify as co-signers or withstand years of repayment.
Cost may therefore likely become a greater part of the admissions decision on both sides. Students must determine whether they can credibly pay for every year required to finish, while universities must decide how much support an admitted student needs before acceptance can become enrollment. How this all shakes out, though, only time will tell.